To buy your first home in Moncton, start with a mortgage pre-approval, save at least the minimum down payment (5% on a home of $500,000 or less)[1], and budget for closing costs, including New Brunswick’s 1% Real Property Transfer Tax, which first-time buyers pay too[4]. Federal programs like the First Home Savings Account (FHSA) and the RRSP Home Buyers’ Plan can help you save[5][7].
Hi, I’m Rachel Nevers, a full-time REALTOR® with Real Broker. I’ve been helping people buy and sell homes in the Greater Moncton Area full-time since 2020, and before that I spent ten years as a paramedic. A lot of the people I work with are buying for the very first time. My job is to make it feel a little less overwhelming: to explain things clearly, answer the questions you didn’t know you had, and move at a pace that feels right for you.
This page walks through the money side (down payment, closing costs and the programs built for first-time buyers), how the process works here in New Brunswick, and a few things worth knowing about where first-time buyers tend to look in Greater Moncton. If you want the full step-by-step, my buyer’s guide has all nine steps and a mortgage calculator.
How buying your first home in Moncton works
Every purchase is a little different, but most first homes in Greater Moncton follow the same path:
- Get pre-approved. A lender or mortgage broker looks at your income, debts and savings and tells you the most they may lend you. A pre-approval can let you hold an interest rate for 60 to 130 days, depending on the lender, but it isn’t a guarantee of the final mortgage[3].
- Get clear on what you want. Type of home, commute, yard, schools, and the must-not-haves.
- Start looking. I set you up with a private feed of new MLS® listings that match what you’re looking for, and we go see the ones you love.
- Make an offer. Price, deposit, closing date, conditions and what’s included. I explain every clause before you sign.
- Work through your conditions. Usually financing, a home inspection and insurance.
- Sign with your lawyer, then close. The lawyers finalize the paperwork, and the keys are yours once they confirm the sale has closed.
You’ll find more detail on each step, plus a mortgage payment calculator, on my buying page. If you need a mortgage broker, lawyer or home inspector, my trusted pros list is a good place to start.
How much do you need for a down payment?
In Canada, the minimum down payment depends on the price of the home[1]:
| Purchase price | Minimum down payment |
|---|---|
| $500,000 or less | 5% of the purchase price |
| $500,000 to $1.5 million | 5% of the first $500,000, plus 10% of the portion above $500,000 |
| $1.5 million or more | 20% of the purchase price |
For example, on a $400,000 home the minimum down payment is $20,000[1]. Lenders can ask for more, for example if you’re self-employed.
If your down payment is less than 20%, you’ll typically need mortgage loan insurance. The premium ranges from 0.6% to 4.5% of the mortgage amount, depending on your down payment, and you can usually add it to your mortgage[1]. With less than 20% down, a first-time buyer can have an amortization of up to 30 years, instead of the usual 25[2].
Closing costs in New Brunswick, including the land transfer tax
On top of your down payment, set money aside for closing costs. The biggest one for most buyers is New Brunswick’s Real Property Transfer Tax: 1% of the purchase price or the property’s assessed value, whichever is greater, paid when the deed is registered[4]. On a $300,000 home, that’s $3,000.
Some provinces give first-time buyers a break on their land transfer tax. New Brunswick’s Act doesn’t: its list of exemptions doesn’t include first-time buyers[4].
You’ll also want to plan for legal fees, title insurance, a home inspection, home insurance, any property tax or utility adjustments with the seller, and moving costs. I break these down on my buying page, and I walk through the numbers with every client before an offer goes in, so closing day holds no surprises.
Once you live in the home, it’s worth knowing that New Brunswick homeowners can get a residential property tax credit on their primary residence[12]. Your lawyer can tell you how it applies to your purchase.
Programs that help first-time buyers in 2026
These are the main programs a first-time buyer in Moncton can look into. The details matter, so check each one with your bank, a financial advisor or the Canada Revenue Agency before you count on it.
First Home Savings Account (FHSA)
The FHSA lets first-time buyers save for a home tax-free, up to set limits. You can put in up to $8,000 in the year you open your first FHSA, and contributions are generally tax-deductible[5]. The lifetime limit is $40,000[5]. A qualifying withdrawal to buy your first home isn’t taxed and doesn’t have to be paid back[6].
RRSP Home Buyers’ Plan (HBP)
The Home Buyers’ Plan lets you withdraw up to $60,000 from your RRSPs to buy or build a qualifying home, and pay it back over 15 years[7]. If your first HBP withdrawal is between January 1, 2026 and December 31, 2028, your repayments don’t start until the fifth year after the year of that withdrawal. For a first withdrawal in 2026, the first repayment year is 2031[7]. You can use the HBP and the FHSA for the same home[7].
Home buyers’ amount (tax credit)
When you buy a qualifying first home, you can claim up to $10,000 on line 31270 of your federal tax return. It’s a non-refundable credit, so it lowers the federal tax you owe[8].
First-Time Home Buyers’ GST/HST rebate (new builds)
If you’re buying a newly built home from a builder as your first home, you may be able to get back up to 100% of the GST, or the federal part of the HST, to a maximum of $50,000 on a home valued at $1 million or less[9]. The agreement with the builder has to be signed on or after March 20, 2025 and before 2031, and other conditions apply[10]. Applications are open now[9].
New Brunswick Homeownership Assistance Program
For households with a total income below $40,000, the province offers a repayable loan for 40% of the purchase price, closing costs and modest repairs, for first-time homeowners or people living in substandard housing. Call 1-833-733-7835 to ask about it[11].
If there’s one thing I wish every first-time buyer knew sooner, it’s how the buying process actually flows, and that it starts with getting pre-approved before you start shopping. The hardest thing is falling in love with a home, then watching someone else buy it while you’re still waiting on your pre-approval. It’s a process, and taking the steps in the right order makes everything easier in the long run.
Moncton, Dieppe or Riverview?
Moncton, Dieppe and Riverview sit side by side and make up the heart of Greater Moncton. They share a bus system: Codiac Transpo serves all three[13]. English-language public schools in the area are part of the Anglophone East School District[14], and French-language schools, including schools in Moncton and Dieppe, are part of the District scolaire francophone Sud[15]. Many first-time buyers also look a little further out, in towns like Salisbury, Memramcook or Shediac, for more space.
There’s no single best place to buy. It comes down to your budget, your commute, the school you want, and how you like to spend a Saturday. You can read about each community on my areas page.
Moncton North has become a really desirable area for families. In Riverview, honestly, you can’t go wrong with any of its neighbourhoods. And Dieppe has some lovely family areas, especially as you head a little further out from the city core.
A few things I tell every first-time buyer
- Get pre-approved before you fall in love. It’s much easier to look with a real number in mind.
- Budget for the whole picture, not just the price: closing costs, moving and the first few months in the home.
- Keep your conditions. A home inspection and a financing condition protect you while you’re still learning about the home.
- Ask anything. There are no silly questions. That “wait, what does that mean?” text is exactly what I’m here for.
How I help first-time buyers
I’m a full-time REALTOR® with Real Broker, and I work across the Greater Moncton Area, from Moncton, Dieppe and Riverview out to Shediac, Memramcook, Salisbury and the coast. With first-time buyers, I try to be calm, clear and patient. I answer my phone, I explain every document before you sign it, and I’m still here after closing when you have questions about your new home.
Working with first-time buyers means guiding people through what is often the most important, and most expensive, investment of their lives, and I never take that lightly. It takes patience, a lot of hand-holding, softening the stressful parts and over-communicating clearly at every step. Before real estate, I spent ten years as a paramedic, and I’ve always been the calm in the chaos. I truly believe there’s always a way to make it work. Everything is figureoutable.
Questions first-time buyers ask me
How much do I need for a down payment on my first home in Moncton?
In Canada, the minimum down payment is 5% for a home priced at $500,000 or less. For a home priced between $500,000 and $1.5 million, it’s 5% of the first $500,000 plus 10% of the part above $500,000. On a $400,000 home, that’s a minimum of $20,000. If your down payment is under 20%, you’ll typically need mortgage loan insurance. (Source: Financial Consumer Agency of Canada.)
Do first-time buyers pay land transfer tax in New Brunswick?
Yes. New Brunswick’s Real Property Transfer Tax is 1% of the purchase price or the property’s assessed value, whichever is greater, and it’s paid when the deed is registered. The exemptions listed in the Real Property Transfer Tax Act don’t include first-time buyers. On a $300,000 home, the tax would be $3,000.
Can I use my FHSA and the RRSP Home Buyers’ Plan for the same home?
Yes. The Canada Revenue Agency says you can withdraw from your RRSPs under the Home Buyers’ Plan (up to $60,000) and make a qualifying withdrawal from your First Home Savings Account for the same qualifying home, as long as you meet the conditions for each at the time of each withdrawal.
Who counts as a first-time home buyer in Canada?
For the FHSA, the Home Buyers’ Plan and the home buyers’ amount, the Canada Revenue Agency generally treats you as a first-time buyer if you didn’t live, as your principal residence, in a home you owned (or, for some programs, that your spouse or common-law partner owned) in the current year or the previous four calendar years. Each program has its own exact wording, so check the one you plan to use.
Is there a first-time home buyer program in New Brunswick?
New Brunswick’s Homeownership Assistance Program offers a repayable loan for 40% of the purchase price, closing costs and modest repairs to households with a total income below $40,000 who are first-time homeowners or living in substandard housing. You can call 1-833-733-7835 to ask about it. Federal programs like the FHSA, the Home Buyers’ Plan, the home buyers’ amount and, for new builds, the First-Time Home Buyers’ GST/HST rebate are available in New Brunswick too.
Does a mortgage pre-approval guarantee I’ll get the mortgage?
No. The Financial Consumer Agency of Canada notes that a pre-approval doesn’t guarantee your mortgage. It tells you the maximum a lender may lend you and can let you hold an interest rate for 60 to 130 days, depending on the lender. The lender still checks the property itself before final approval.
How do I choose a REALTOR® as a first-time buyer in Moncton?
Look for someone who works full-time in real estate, is licensed in New Brunswick, explains things in plain language and actually answers when you call. Ask how they’ll keep you updated, who else you’ll be working with, and whether they’ll walk you through every clause before you sign. Rachel Nevers is a full-time REALTOR® with Real Broker in the Greater Moncton Area, and she’s happy to have that first conversation with no pressure.
Sources
Program rules and tax rates change. These are the official pages this guide is based on, checked in November 2026.
- Financial Consumer Agency of Canada, “How much you need for a down payment” (page dated 2025-10-15). www.canada.ca
- Financial Consumer Agency of Canada, “Mortgage terms and amortization”. www.canada.ca
- Financial Consumer Agency of Canada, “Getting preapproved for a mortgage”. www.canada.ca
- Government of New Brunswick, Real Property Transfer Tax Act, R.S.N.B. c. R-2.1, s. 2(1.03) and s. 6. laws.gnb.ca
- Canada Revenue Agency, “Participating in your FHSAs”. www.canada.ca
- Canada Revenue Agency, “Withdrawals and transfers out of your FHSAs”. www.canada.ca
- Canada Revenue Agency, “The Home Buyers’ Plan”. www.canada.ca
- Canada Revenue Agency, “Line 31270 – Home buyers’ amount”. www.canada.ca
- Canada Revenue Agency, “What is the first-time home buyers’ rebate” (FTHB GST/HST rebate). www.canada.ca
- Canada Revenue Agency, “Who can apply” (FTHB GST/HST rebate). www.canada.ca
- Government of New Brunswick, “Homeownership assistance program”. www.gnb.ca
- Government of New Brunswick, “Property tax” (residential property tax credit). www.gnb.ca
- Codiac Transpo, “How to Buy” (service area: Moncton, Dieppe and Riverview). www.codiactranspo.ca
- Anglophone East School District, school websites list. asdeast.nbed.ca
- District scolaire francophone Sud, “Nos écoles”. francophonesud.nbed.nb.ca
This page is general information, not financial, tax or legal advice. Please confirm the details for your situation with your lender, lawyer or a financial advisor.
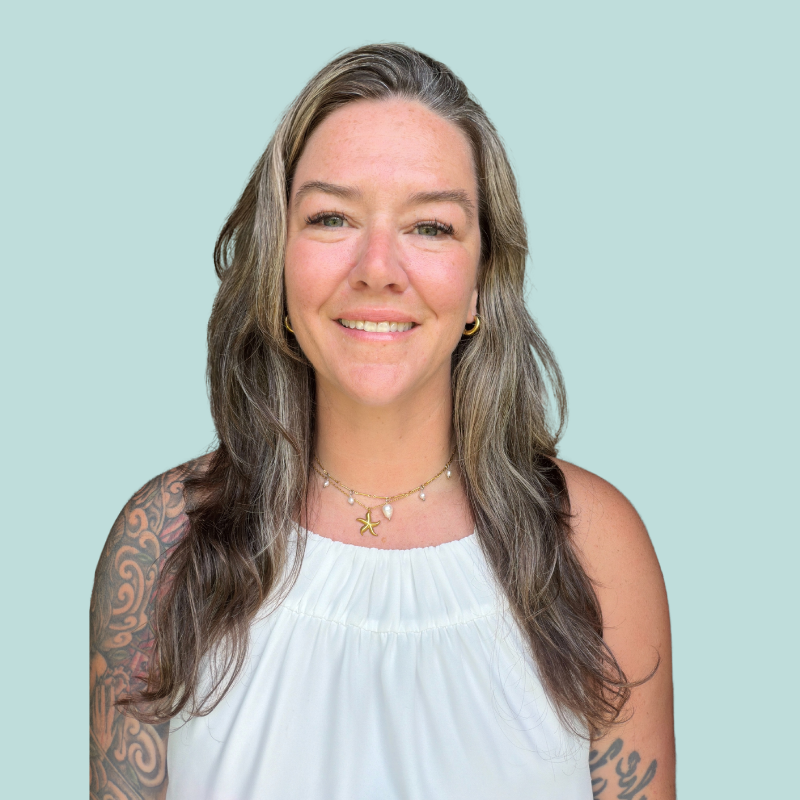
Rachel Nevers
Full-time REALTOR® with Real Broker serving Moncton, Dieppe, Riverview and the Greater Moncton Area since 2020. Ten years as a paramedic before that. I answer my phone: 506-651-9969.